 Customer Login
 GRO Score

 Home
 About
 Products
 Investors
 Partners
 In The Media
 Contact Us
 Customer Login
Should You Invest or Buy a House First?
Buying a house or investing first? Explore the financial trade-offs with UGRO Capital. Read our guide to make an informed choice.
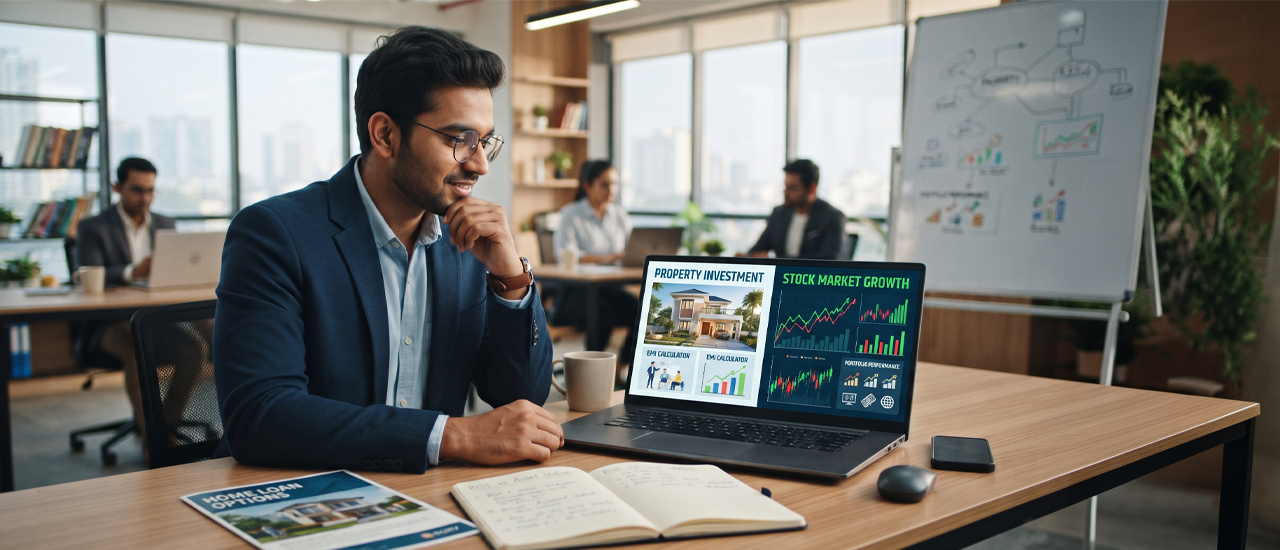
It's one of the most common financial dilemmas for young earners in India: put savings into mutual funds and equities, or set them aside for a home down payment? There isn't a single right answer — it depends on your finances, timeline, and life plans — but understanding the trade-offs on both sides makes the decision much easier.
The Case for Investing First
Market-linked investments — equities, mutual funds, and similar instruments — have historically offered stronger long-term returns than most other asset classes, and crucially, they're liquid. You can start with small, regular amounts through a SIP, stay flexible if your income or plans change, and compound wealth over time without committing to a large, long-term liability. For someone early in their career, with an uncertain job location or evolving life plans, this flexibility often matters more than people initially realise.
The downside is volatility. Market-linked returns aren't guaranteed year to year, and money invested for a near-term goal can be at risk if markets dip right when you need to withdraw.
The Case for Buying a House First
A home offers something markets don't: a fixed, usable asset and freedom from rent, along with the psychological comfort of ownership and stability for a family. Home loan EMIs also function as a form of forced, disciplined saving, and tax benefits on home loan principal and interest can meaningfully reduce the effective cost of ownership.
The trade-offs are real too. Real estate is illiquid — you can't sell a portion of your house to cover an emergency the way you can redeem part of a mutual fund. Property also ties up a large amount of capital in a single, undiversified asset, and comes with ongoing costs: maintenance, property tax, and registration charges that add to the effective cost of ownership.
Questions Worth Asking Yourself
- How long do you plan to stay in one city? A home makes more sense when you're reasonably settled; frequent relocation favours staying liquid.
- Do you have an emergency fund separate from this decision? Committing all your savings to either a down payment or a lump-sum investment, with nothing held back, adds risk either way.
- What does the EMI do to your monthly cash flow? A home loan that stretches your budget too thin can crowd out the very savings and investing habit you're trying to build.
- Is this a need or a goal you're optimising for returns on? A home you'll actually live in is a lifestyle decision as much as a financial one; a second property bought purely for appreciation should be judged more like any other investment.
A Middle Path
For many people, the realistic answer isn't "either/or." Building a modest investment portfolio alongside a disciplined down-payment fund — rather than deferring one entirely for the other — lets you capture market growth while still working steadily towards ownership. And if a home purchase is a few years out, a Loan Against Property or home loan can help you time the purchase around when it genuinely makes sense for your life and finances, rather than rushing in or delaying indefinitely out of indecision.
It also helps to revisit this decision periodically rather than treating it as a one-time choice made in your twenties. Income, city, family plans, and even interest-rate cycles shift over a few years, and what made sense when you started saving may not be the best order of priorities five years later. Reviewing your goals annually — rather than locking into a plan and never revisiting it — tends to produce better outcomes than getting the initial decision "perfectly right."
There's no universally correct order here — only the order that fits your income stability, timeline, and risk appetite. This is informational content, not personalised financial advice; it's worth speaking with a financial advisor about your specific situation before making a decision of this size.
Explore UGRO Capital's Home Loan and Loan Against Property solutions to learn more.