 Customer Login
 GRO Score

 Home
 About
 Products
 Investors
 Partners
 In The Media
 Contact Us
 Customer Login
Home Loan for Self-Employed
Explore home loan eligibility for self-employed individuals, required documents, and tips to improve approval chances with UGRO Capital.
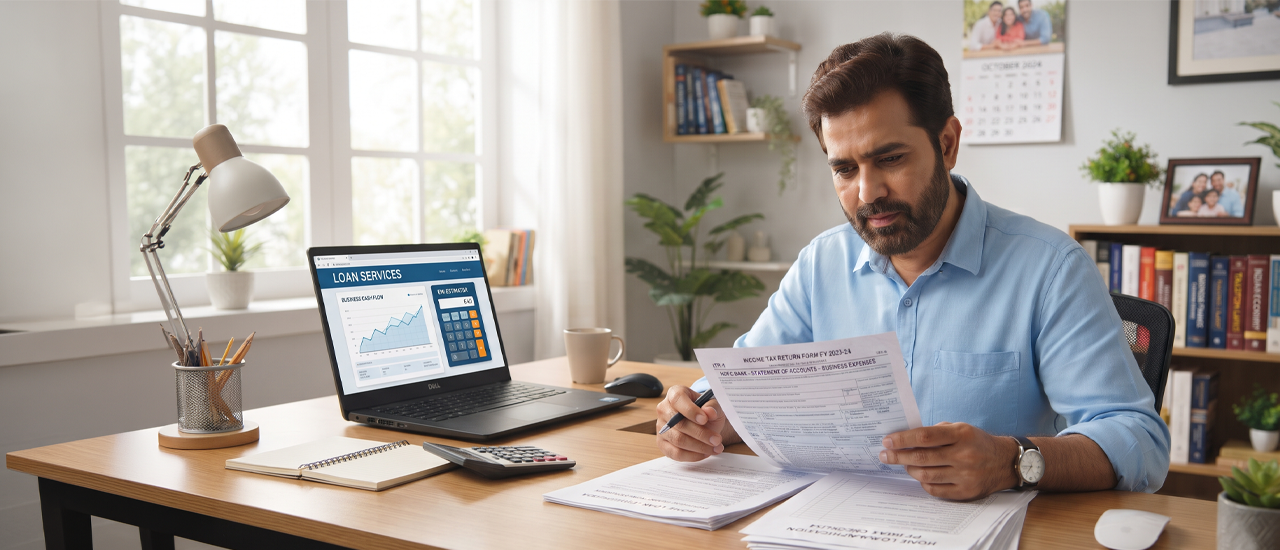
If you run your own business or work as a professional — a shop owner, consultant, doctor, or trader — you've probably noticed that home loans don't feel designed for you. Salaried applicants walk in with a salary slip and Form 16; self-employed applicants have to prove the same thing — steady, reliable income — with a very different set of documents. Here's how it actually works.
Why Lenders Assess Self-Employed Applicants Differently
A salaried applicant's income is predictable and verified by an employer every month. A self-employed applicant's income can vary by season, by client, or by business cycle — even when the underlying business is healthy and growing. Because of this, lenders don't just look at your latest income figure; they look at the trend across two to three years, the stability of your business, and your ability to service the EMI through both strong and slow months, not just your best month.
Documents You'll Typically Need
- Income proof: ITRs for the last 2-3 years, along with computation of income, for yourself and your business if applicable.
- Business proof: GST registration, business registration or licence, and proof of business continuity (typically 3+ years is preferred).
- Financial statements: audited or CA-certified profit and loss statement and balance sheet for recent years.
- Bank statements: both personal and business account statements, usually for the last 6–12 months, to show cash flow patterns.
- KYC and property documents: identity and address proof, along with the usual property-related paperwork for the home being purchased.
How Lenders Evaluate Your Eligibility
Beyond the documents, most lenders look at a combination of factors: your net profit trend (growing, flat, or declining), your debt-to-income ratio including any existing business loans, your credit score and repayment history, and increasingly, your digital footprint — GST filings, banking transaction patterns, and formal digital payments — which help build a fuller picture of business health beyond what the ITR alone shows. This is particularly relevant for small business owners whose income may be understated on paper relative to actual cash flow.
Tips to Improve Your Approval Odds
- File your ITRs consistently and on time. Gaps or irregular filing are one of the most common reasons self-employed applications get delayed or declined.
- Keep business and personal finances separate. Mixed transactions make it harder for a lender to read your actual income clearly.
- Maintain a healthy credit score. Timely repayment of existing loans and credit cards matters just as much for self-employed applicants as for salaried ones.
- Consider a co-applicant. Adding a spouse or family member with stable income can improve eligibility and may also open up a higher loan amount.
- Choose a lender that understands small-business income. Not every lender evaluates self-employed applicants the same way — some rely purely on ITR figures, while others assess cash flow and business potential more holistically.
Why This Matters
For India's large self-employed and small-business population, access to home financing shouldn't depend on fitting into a salaried-income template. This is exactly where lenders built around small-business underwriting, rather than conventional salary-slip assessment, make a real difference. At UGRO Capital, home loan and secured lending decisions for self-employed and small-business borrowers draw on GST data, banking patterns, and credit bureau information through our proprietary GRO Score, alongside the usual documentation — helping assess income the way a small business actually earns it, not just the way it appears on paper.
None of this means approval is guaranteed or that documentation requirements disappear — a stable, well-run business with clean records will always have an easier path than one with erratic income or patchy filings. But it does mean the assessment can be fairer: a good year shouldn't be erased by one slow quarter, and a business that's clearly growing shouldn't be judged solely on a conservative income figure from three years ago.
Explore Financing Solutions with UGRO Capital
Self-employed individuals and small-business owners may need financing options that account for their business income and repayment capacity. UGRO Capital uses its proprietary GRO Score, alongside credit bureau information and banking patterns, to assess the financial profile of eligible borrowers.
If you own a property and are exploring funding options, discover UGRO Capital's Loan Against Property solutions to understand the available financing options and eligibility requirements.
Explore UGRO Capital's Home Loan solutions to learn more.