 Customer Login
 GRO Score

 Home
 About
 Products
 Investors
 Partners
 In The Media
 Contact Us
 Customer Login
Home Loan for Growing Families: When It's Time to Move Into Something Bigger
Planning to move into a bigger home? Explore home loan options, financial readiness, and how a Loan Against Property can help fund your upgrade.
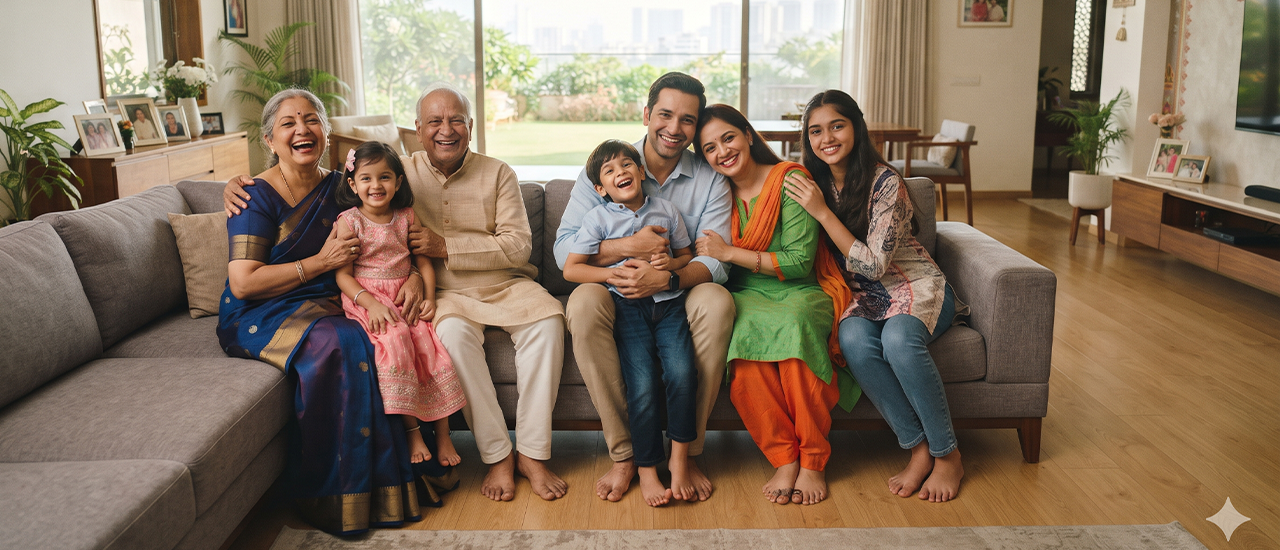
The home that comfortably fit a young couple rarely fits the same family five or ten years later. A new child, ageing parents moving in, or simply a work-from-home setup that needs its own room — at some point, most growing families start asking the same question: is it time to move into something bigger? Here's how to think through that decision, and how a home loan fits into it.
Signs You've Outgrown Your Current Home
- Space is a daily friction point. If storage, study space, or simply having separate rooms for kids has become a recurring source of stress rather than an occasional inconvenience, that's a strong signal.
- Your household composition has changed. A new baby, parents moving in, or a live-in relative changes space needs in ways a 1BHK or 2BHK often can't absorb.
- You're renting storage or working around the home. Paying for external storage, or routinely working from a dining table because there's no study, is often a sign the current home has already been outgrown financially and practically.
- You plan to stay in the same city long-term. Upgrading makes far more sense when you're reasonably settled than if a relocation is likely in the next couple of years.
Checking Your Financial Readiness
Before house-hunting, it helps to look at the numbers honestly. Start with your existing home loan, if any — how much equity have you built, and what would selling or renting out the current home realistically add to your down payment? Next, look at your income stability and existing EMI obligations: lenders typically want total EMIs, including the new loan, to stay within a manageable share of monthly income, and so should you, regardless of what you technically qualify for. Finally, account for the full cost of moving — registration, brokerage, interiors, and shifting expenses — which often gets underestimated against the loan amount alone.
How a Home Loan Supports the Move
For most growing families, a home loan (or a top-up on an existing one) is what bridges the gap between the current home's equity and the cost of a bigger one. A few structures are worth knowing:
- Fresh home loan: taken against the new property, often alongside proceeds from selling the existing home.
- Balance transfer with top-up: moving your existing loan to a new lender at better terms while borrowing additional funds for the upgrade, useful if you're not selling the current home outright.
- Loan Against Property: if you own the current home outright or have significant equity in it, using it as collateral can fund a down payment on the next one without liquidating other investments.
Tenure matters here more than it might seem. Stretching a loan to the maximum tenure lowers the EMI but increases total interest paid — worth weighing against your stage of life and how many working years you have left to repay comfortably.
Making the Move Work for Your Family
A bigger home is ultimately a lifestyle decision wrapped in a financial one. It's worth resisting the pressure to buy the maximum space your loan eligibility allows, and instead sizing the move to what your family actually needs for the next several years — not just what feels aspirational today. A slightly smaller, well-located, financially comfortable upgrade tends to serve a growing family better over time than a larger home that stretches the budget thin from day one.
It also helps to time the move around your family's milestones rather than purely around market conditions. Waiting for the "perfect" interest rate or property price often costs more in rent, storage, or daily friction than it saves — while moving before your finances are genuinely ready can strain the household for years. The right time, in most cases, is when your space needs and your loan eligibility are both comfortably aligned, not just one or the other.
Fund Your Next Move with a Loan Against Property
Planning to upgrade to a bigger home while managing your existing financial commitments? A Loan Against Property can help eligible property owners unlock funds against their residential or commercial property to meet business or other eligible financial needs. Before choosing this option, assess your repayment capacity, applicable interest rates, and loan terms to ensure the borrowing fits your financial plans.
Explore UGRO Capital's Home Loan and Loan Against Property solutions to learn more.